



Archives
Feature, Freight News, Logistics, People, Sea
Multipurpose Sentiment Hits Four-year High
[ November 5, 2026 // Gary Burrows ]Multipurpose and breakbulk carrier sentiment has reached its highest level since early 2022, with operators expecting tightening vessel availability to persist even if geopolitical chokepoints begin reopening.
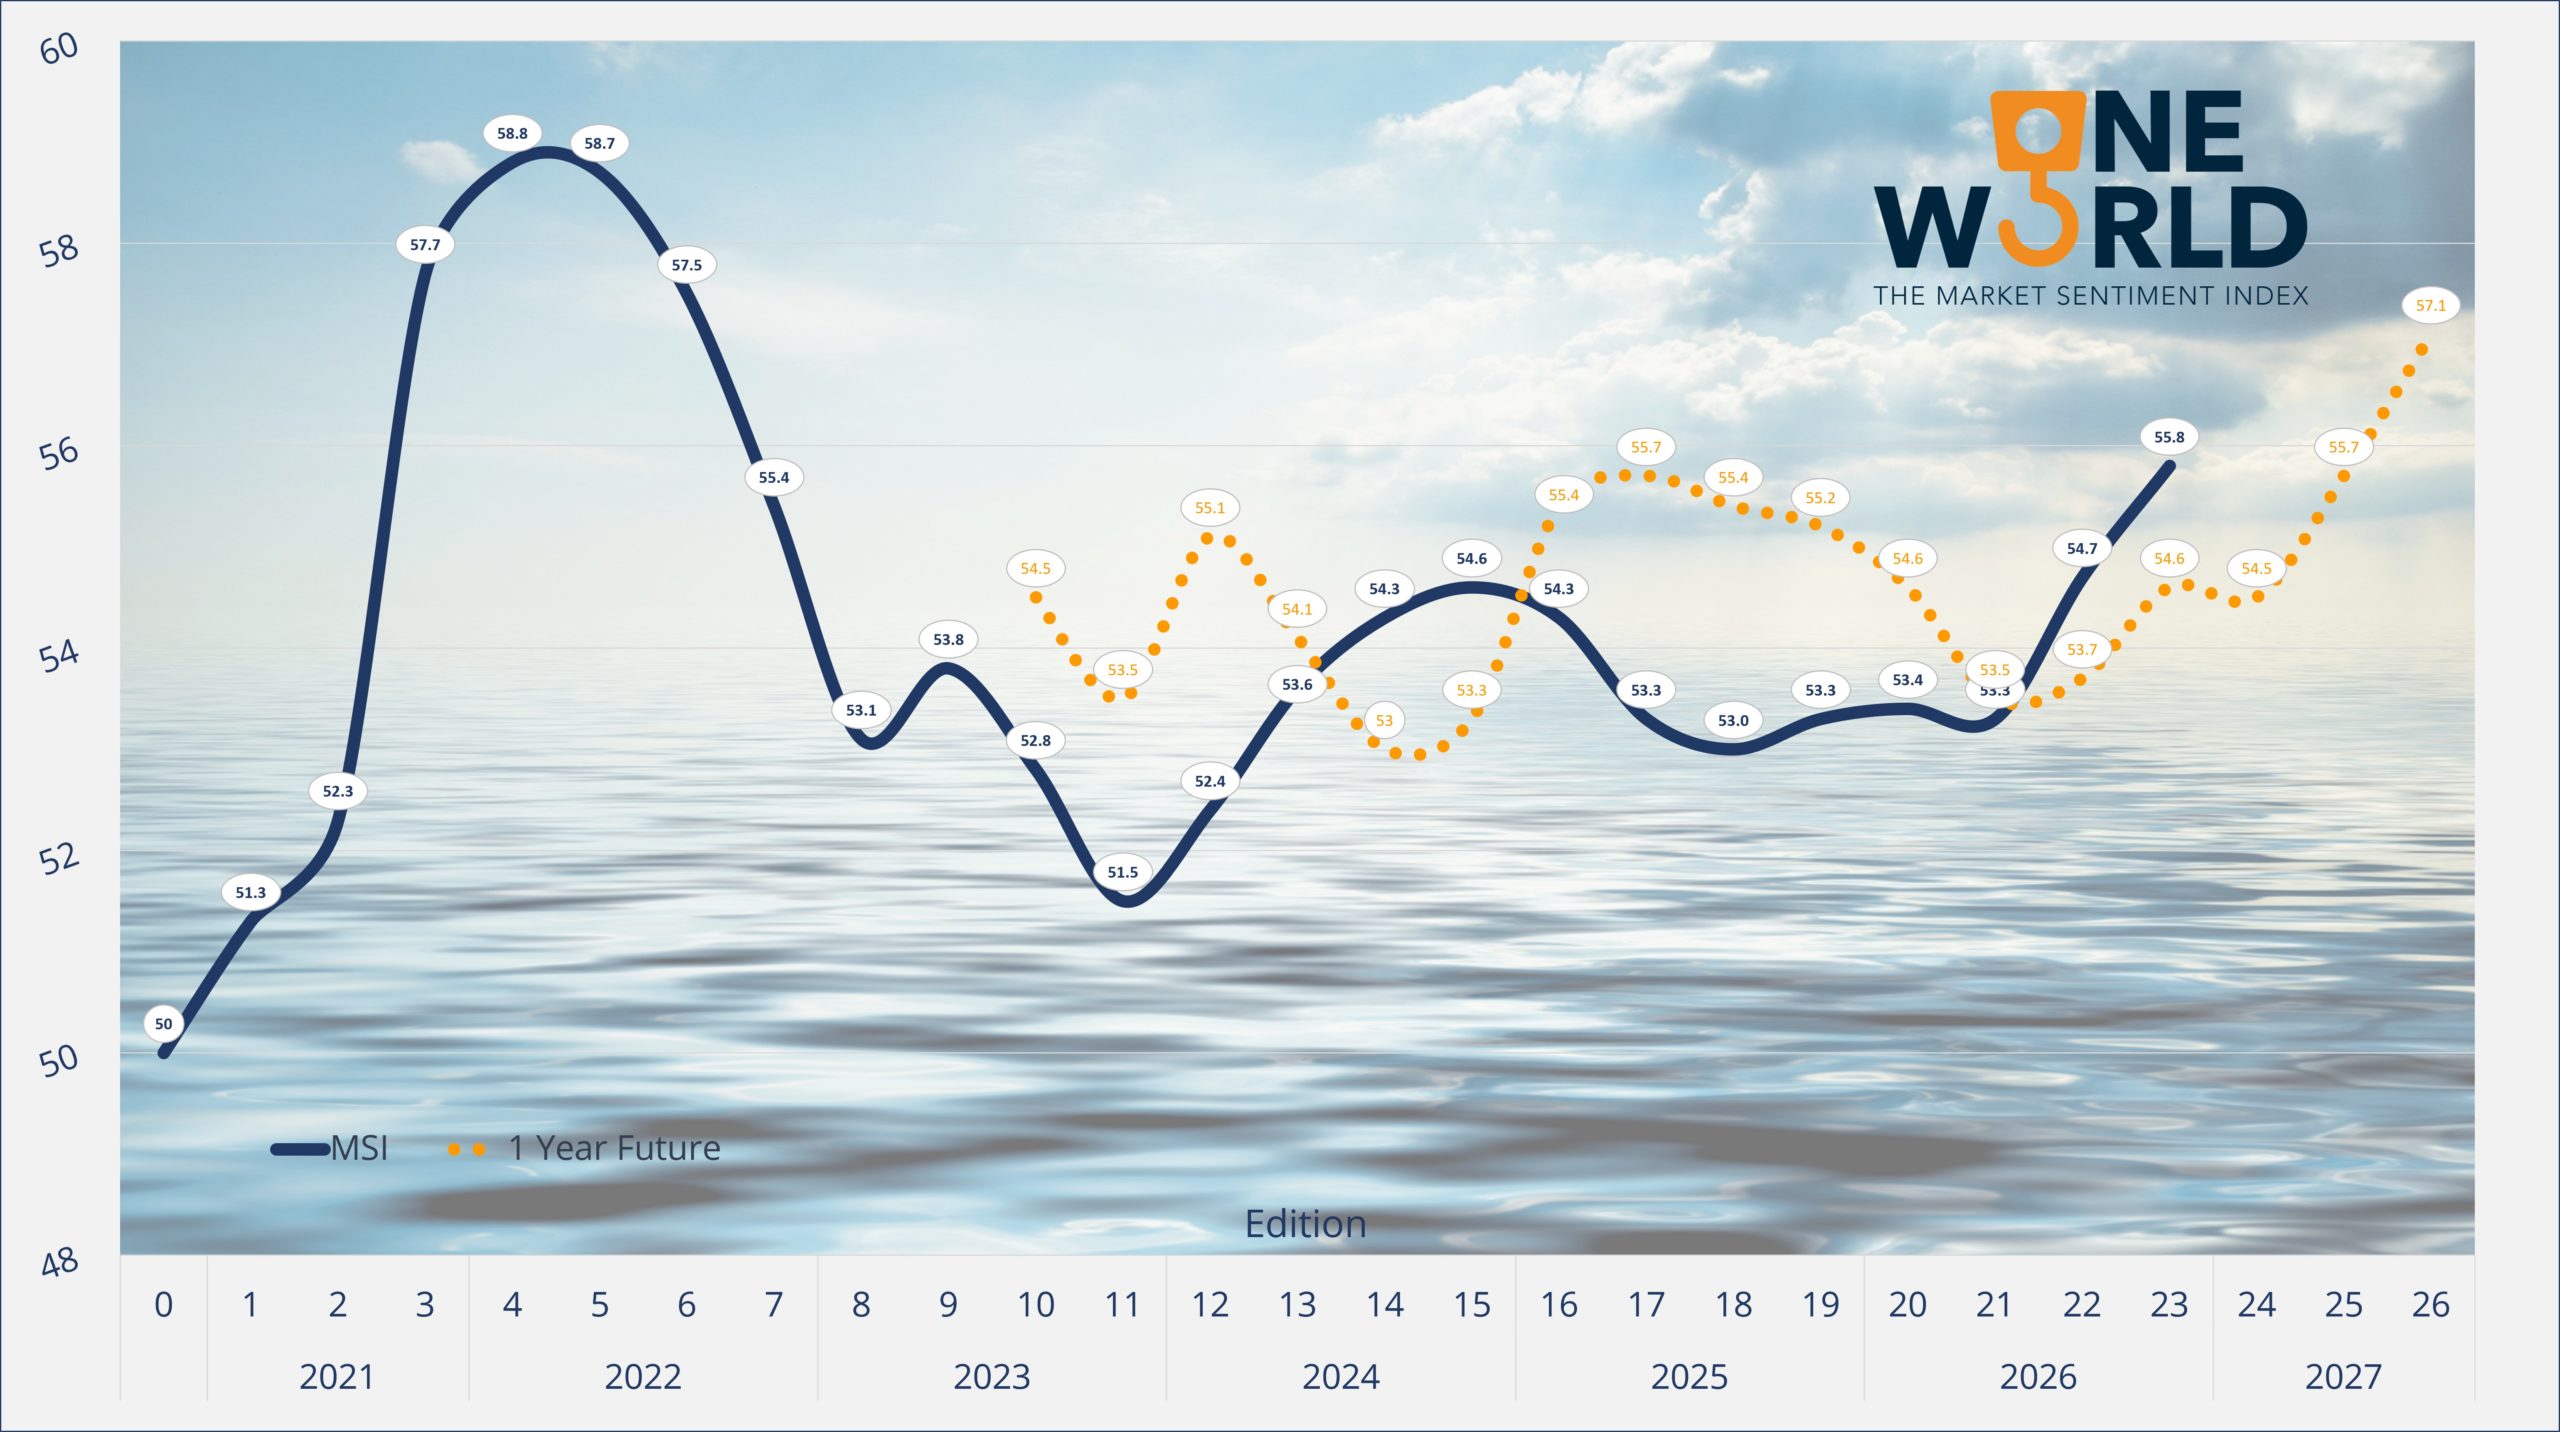
The Market Sentiment Index for the multipurpose and breakbulk shipping industry rose to 55.8 in the fourth quarter, extending its recovery for a second consecutive period. Twenty of the 27 participating carriers reported stronger sentiment than three months earlier, six were unchanged and one reported a decline.
The index’s 12-month outlook points to further improvement, reaching approximately 57 by the third quarter of 2027. The report said the forward trajectory indicates a market continuing to strengthen over the coming year.
The improvement is being driven less by a major increase in cargo volume than by disruptions absorbing effective vessel supply. Longer voyages, port congestion, Middle East security risks, Panama Canal constraints and elevated operating costs are reducing the number of voyages vessels can complete.
The index’s current vessel-supply indicator fell below the neutral level of 50 for the first time, signaling that carriers believe cargo demand is exceeding available capacity. Time-charter expectations increased almost 4 percent to 56.1, their highest level since early 2023.
Justin Archard of One World Shipbrokers, which produces the index, said the eventual reopening of the Red Sea and Persian Gulf does not necessarily make the current squeeze temporary within the market’s practical planning horizon.
Even after the routes are technically navigable, operators will require time to regain confidence following attacks and vessel losses, he said. Most project cargo is booked within a six- to 12-month horizon, making that transition period commercially significant.
“There will be no industry-wide rush to return to hot spots unless security can be guaranteed,” Archard told FBJNA.
He said the index’s one-year outlook strengthened following the start of the conflict with Iran, adding momentum to a firming trend that began in 2023.
Reopening could also release pent-up demand for projects and reconstruction in affected regions. That cargo could draw vessels back into the Middle East and absorb capacity that otherwise might return to competing trades.
“Trend tightening is going to very likely continue irrespective of whether chokepoints ease,” Archard said, citing responses from participating carriers.
The index’s feature survey asked operators whether geopolitical and economic volatility represented a headwind or tailwind. On a scale of one to 10, the average response was 6.3, with 83 percent of respondents rating current conditions as a tailwind to varying degrees.
Asian carriers reported the strongest sentiment, followed by carriers in the Americas and Europe. The report attributed Asia’s position partly to export demand and bottlenecks affecting Red Sea ports. Operators in the Americas reported stronger inbound cargo volumes but continued uncertainty surrounding Panama Canal access and costs.
The outlook also points to an aging fleet. The average age of geared multipurpose vessels with lifting capacity above 100 tonnes exceeds 16 years, while the orderbook represents about 3 percent of existing fleet deadweight.
Archard said the limited orderbook is not necessarily the immediate constraint because owners can extend the operating lives of older vessels while market conditions support them. New orders placed now would also take years to enter service.
In a weak market, shippers may resist older vessels, he said. When capacity is scarce, however, cargo interests are more likely to accept available tonnage to keep shipments moving. Older vessels could therefore remain the backbone of multipurpose shipping for years.
Newbuilding deliveries are barely reaching replacement levels, while time-charter rates remain below those needed to support investment in many cases, Archard said. That has limited speculative ordering and allowed established operators to maintain a disciplined approach to fleet expansion.
Energy security, refining investment, power infrastructure and eventual reconstruction in Ukraine and the Middle East could create additional project cargo demand. Against that outlook, the report raises the prospect that the multipurpose and heavy-lift market may be moving toward a more structural capacity shortage rather than experiencing only a temporary disruption.
Multipurpose Sentiment Strengthens
Tags: Julian Archard, Market Sentiment Index, One World Shipbrokers